When we first decided to live on one income in Australia, it felt limiting. We were both working, but we made a decision to live on just one of our incomes and put the other towards paying off our debt.
At first, it felt like we were giving things up. What I didn’t expect was how much freedom that decision would eventually give us.
This is the story of how that happened, what we cut back on, and why we’re still living on one income today.
Where we were when we started
We arrived in Australia in 2016. Our first years here weren’t easy. My husband couldn’t find work for the first 12 months, and when he finally did, he lost that job six months later. I found work before he did, and for a long time our money felt like it was always wobbling.
By the time we were both working, we were settled. But we were busy every day with work, our daughter and family. And at the end of every month, there was nothing much left. We had debt, and it didn’t seem to be getting any smaller.
We were earning, but our money wasn’t moving us forward. That was the part that hurt the most.
The decision: one income to live on, one income with a job to do
Living on one income sounds simple. But it meant our day-to-day life had to fit inside one pay. Rent, groceries, bills, school costs, everything.
The second income wasn’t “extra money” anymore. It had a job. And its job was to clear our debt.
How it felt at first
I’ll be honest. In the beginning, it felt like we were working on a limited budget. Every time we said no to something, it felt like we were going without.
If you’ve ever been in that place, you may know the feeling. You see what other people are spending, and you wonder if you’re missing out. You wonder if all this effort will actually make a difference.
That feeling didn’t last forever, though. Something shifted once we really understood why we were doing it.
The shift: cutting back because of a priority, not a lack
This is the part I most want you to hear. We weren’t cutting back because we didn’t have money. We were making room for something more important to us.
When you cut back because you feel you have no choice, it can feel heavy. When you cut back because you’ve chosen where your money goes, it can feel liberating.
It isn’t about how small your income is. It’s about directing your income into the things that actually move your finances forward. Once that clicked for us, saying no to takeaway on a Friday night didn’t feel like a loss. It felt like a yes to something bigger.
What we cut back on
These were the changes that made the biggest difference for our family. None of them were dramatic on their own. Together, they added up.
1. Eating out
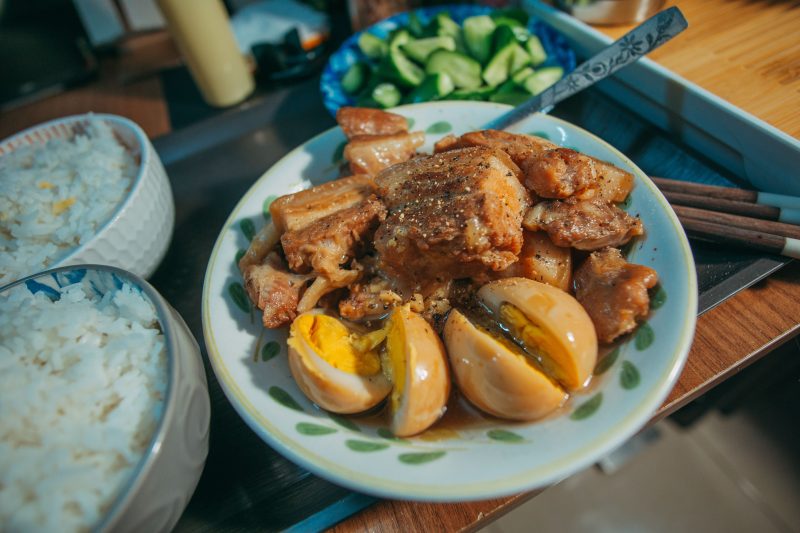
We made eating out an occasional treat rather than something we did regularly. Meals at home became our normal.
2. Takeaways
We started planning meals at home so we weren’t relying on takeaway after a long day. It was one of the easiest spending habits to change.
3. Buying on special
We started planning our grocery shopping around specials. For things we regularly used, we’d buy them when they were on sale rather than paying full price.
4. Staples from Aldi
We bought our everyday staples from Aldi. For our family, it made our grocery shop simpler and more predictable.
5. Growing our own veggies
We started growing some of our own vegetables. It’s a small thing, but it felt good, and it meant a few fewer things on the shopping list.
Your list may look different from ours, and that’s okay. The point isn’t to copy what we cut. It’s to find the spending that matters least to you, so more of your money can go to what matters most.
How we kept track
We tracked everything in an Excel spreadsheet. We also gave every dollar a job. We used four simple categories: Daily Expenses for the needs, Entertainment for the wants, Reward Money for a little guilt-free spending, and an Emergency Fund for the unexpected.
Having those four places for our money meant we weren’t guessing anymore. We didn’t need a complicated budgeting system.
We needed something simple enough to follow consistently.
The spreadsheet didn’t need to be fancy. It just needed to show us the truth about where our money was going. Once we could see it clearly, it was much easier to make decisions that matched our goal.
The moment we knew it was working
We knew it was really working the day we paid off our debt. Once we had a system in place, it took us eight months.
After years of feeling like our money wasn’t going anywhere, that moment meant more than the number on the screen. It was proof that the small choices we’d been making every day were adding up.
It also changed how we saw our own money. We weren’t stuck. We just hadn’t been giving our money a clear direction.
Then we did it again, and again
Here’s the part that surprised us. When the debt was gone, we didn’t go back to spending both incomes. The second income still had a job. We just gave it a new one. The money that had been going to our debt now went to our next goal.
Goal after goal, we used the same simple idea. Live on one income. Give the other one a job.
We’re still living on one income today. It doesn’t feel limiting anymore. It feels like the thing that gave us room to breathe.
If you're thinking about trying this
Every family’s situation is different, and I know not everyone has two incomes to work with. If you’re on one income because that’s all there is right now, please be gentle with yourself. The same idea can still help you, even on a smaller scale.
Here’s what helped us, in case it helps you too.
1. Start with one clear goal
Ours was paying off our debt. Having one goal made every “no” feel like it had a purpose.
2. Choose what to cut by what matters least to you
Don’t cut the things that keep your family going. Look for the spending that doesn’t really add much to your life.
3. Write it down somewhere you'll actually look
For us, it was a spreadsheet. For you, it could be a notebook or an app. What matters is that you can see where your money is going.
4. Expect it to feel tight at first
That feeling is normal. It may ease once you can see your progress.
5. When you reach your goal, give that money a new job
This is where the real change can happen, because the habit keeps working for you long after the first goal is done.
Frequently asked questions
Is it possible to live on one income in Australia?
For our family, yes. We had two working adults but chose to organise our spending around one income. It took some changes to how we spent, especially on eating out, takeaways and groceries.
Whether it works for you may depend on your household income, living costs and family’s needs, so it’s worth looking at your own numbers first.
What should we cut first when living on one income?
We started with the things that were easiest to change and added the least to our lives, like takeaways and eating out. Your list may be different. Look for the spending that matters least to you.
How do you track spending on one income?
We used an Excel spreadsheet and four simple categories for our money. A notebook or an app can work just as well. The most important thing is that you can clearly see where your money is going.
What do you do with the second income?
We gave it one job at a time. First, it went towards paying off our debt. Then it went towards our emergency fund, then saving for our home, and later investing.
How long did it take to pay off your debt?
Once we had a system in place, it took us eight months. Every situation is different, so your timeline may look different from ours.
A gentle next step
If you’d like to put a simple budgeting system in place using your own numbers, our Immigrant Budget Starter Workbook can help you get started.
It includes practical tools to help you understand your spending, organise your expenses and create a clearer starting point for your money.
And if you’re on one income right now, whether by choice or not, I hope you know this. You’re not behind. You may just be one clear goal away from feeling like your money is finally moving.